How Much Money Should You Really Keep in Your Business Account?
There’s no universal number that works for every business. Keep too little cash and every slow payment or unexpected bill creates stress. Keep too much sitting idle and you’re missing better uses for that money. The right balance depends on how steady your revenue is, how fixed your costs are, what stage your business is in, and how much risk you’re comfortable carrying.
Why Cash Reserves Matter
Cash is both a safety net and a tool. It covers gaps when customers pay late, helps you handle slow months, and lets you act on opportunities without scrambling for loans. Businesses running near zero often end up paying higher financing costs, dealing with strained suppliers, and making short-sighted cuts. Having enough breathing room leads to better decisions.
What Shapes the Right Number
Stable, recurring revenue usually means you can run with a thinner reserve. Project-based or seasonal businesses generally need more. High fixed costs—payroll, rent, software—also push the number higher because those bills keep coming even when sales dip. Early-stage companies and those planning big moves often benefit from larger cushions. Industry norms and the broader economy matter too.
A Practical Way to Calculate It
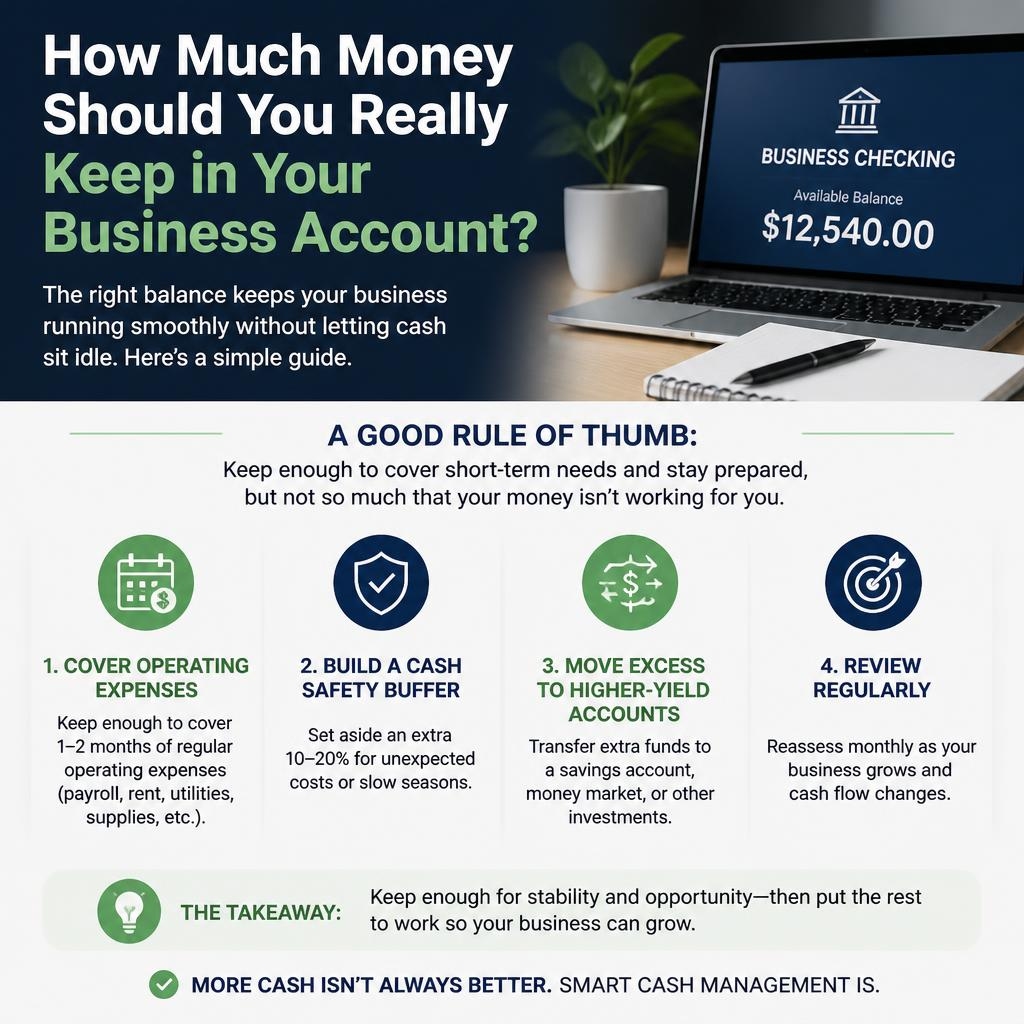
A common starting point is three to six months of essential expenses. Focus on the must-pay items: payroll, rent, utilities, insurance, core tools, and minimum inventory. Then adjust for your reality. If you wait a long time to collect invoices or have to pay suppliers quickly, you’ll need more. Running a few simple “what if” scenarios—normal month, slow month, rough stretch—helps refine the target. Business owners looking for additional financial management advice can browse around this site to explore more useful resources and practical ideas.
Some owners keep operating cash separate from a true reserve. That mental and practical separation makes it harder to spend the safety money on non-essentials.
The Risks on Both Sides
Too little cash turns small problems into big ones. Payroll gets tight, suppliers get nervous, and good opportunities pass by. Stress rises and decision-making suffers.
Too much idle cash has quieter downsides. It earns little and can hide inefficiencies in how you manage receivables, inventory, or spending. In some cases, there are smarter places for that capital.
Building and Keeping the Right Balance
The most reliable way to improve cash is tightening the basics: collect faster, negotiate better supplier terms, and avoid tying up money in excess stock. Profitability still matters—reserves are hard to build if the business isn’t generating cash in the first place. A line of credit can backstop you, but it shouldn’t replace actual cash.
Review the target every few months. Revenue patterns change, costs shift, and plans evolve. Weekly visibility into cash flow and clear rules about spending help keep things on track.
Final Thoughts
Getting this right isn’t about hitting a perfect number once. It’s about matching your cash to the real risks and goals of the business so you can operate with more stability and fewer surprises.